Working Papers
Hausmann, R., et al., 2025
The Malawian economy is currently unable to grow despite the immense potential of its people. Per capita income has been declining since 2020, while poverty remains amongst the highest in […]
The Malawian economy is currently unable to grow despite the immense potential of its people. Per capita income has been declining since 2020, while poverty remains amongst the highest in the world. Equally problematic, Malawi’s growth over the preceding decade was wholly insufficient to keep pace with the rest of the global economy. This kept Malawian per capita income at less than 1% of the U.S. level. Unless problems that have been allowed to fester are reversed, most Malawian families will continue to be subjected to poverty and extreme vulnerability, today and potentially for generations to come. Worse, Malawi is in the midst of a slow-moving macroeconomic crisis which could become deeper and more acute if access to foreign exchange collapses further.
Reversing the course of the national economy is ultimately about putting Malawians in a position to pursue opportunities that are currently held back. Even as the nation has faced nearly annual climate-related shocks, Malawians are resilient. It is their access to productive economic networks that holds back opportunity. Other countries such as Rwanda and Ethiopia that are landlocked, face weather shocks, and were recently as poor as Malawi have been able to achieve accelerated growth paths through long-term investment and growth in exports. Malawians are meanwhile brimming with untapped potential, and Malawian businesses are as enterprising as any in the world. There are many potential opportunities for growth in Malawi from agriculture, mining, tourism, and others that are severely held back by macroeconomic circumstances.
Jumpstarting growth is impossible under current macroeconomic constraints. As growth has lagged, and as Malawi has been subjected to shocks, macroeconomic policy has been put in a bind, which has been increasingly tightening. As late 2025, Malawi faces foreign exchange shortages that have played a critical role in undermining the economy for several years. This shortage has come alongside high inflation, which is undermining the hard-earned incomes of Malawians. Recent investment levels have been insufficient for Malawi’s current needs and have been reliant on increasingly fickle donor support. Private investment is extremely low in Malawi. It is very difficult for both domestic and foreign investors to invest in Malawi’s potential when they cannot import the inputs they need or freely move in and out the dollars their export businesses generate, and when returns are at risk of being inflated away. While solving macroeconomic challenges alone will not create the dynamic export sectors that Malawi needs, it is a necessary condition.
The current macroeconomic environment is causing pain and hardship while putting Malawi in an even more vulnerable position. The government has lost access to external credit, leaving it reliant on a vicious cycle of domestic borrowing from banks at high cost and excess money creation to support current spending. Foreign exchange availability teeters on the edge of collapse, with import coverage measured in units of days or weeks. Access to foreign exchange and finance from domestic banks provides a tenuous lifeline, but this system will break at some point if the balance sheets of banks increasingly deteriorate. All the while, as macroeconomic policy targets survival rather than a strategy for addressing the core problems, the damage of these distortions on the economy and lives of everyday Malawians is immense. Macroeconomic anchors are currently ineffective, and Malawians are growing poorer each day. With buffers so thin, Malawi is one shock away from potentially being in an even worse crisis.
As a result, Malawi has two economic problems: a medium-term growth challenge and a short-term macroeconomic stabilization crisis. It is important to understand each of these clearly and how they interact. This note points to several key observations on the growth challenge and the path out of the macroeconomic crisis. The report is organized around five key conclusions, which do not neatly align with the stated understanding of the Government of Malawi nor that of international development community in all cases.
- First, the path to growth will hinge on expanding exports. Malawi has gotten to this critical point because its traditional sources of foreign exchange (e.g., tobacco and aid) have stagnated or declined while its population grows, and it is hit by increasingly more frequent shocks. Since 2012, this has led to three distinct phases of macroeconomic management to live within lesser means. Growth will require a steady increase in export generation, and strategies should thus pay special attention to what holds back the growth of existing and new exporters. The current macroeconomic regime is clearly untenable but a return to previous regimes is also no longer possible. The regime that allowed for a fixed exchange rate and low inflation over 2017-2020 is no longer possible because it relied on positive net foreign reserves that were available at the time. Policymakers will need to develop a new path that is built on generating exports and foreign investment. Such a path will need to both solve the current macro issues and remove restrictions and barriers in areas like land, access to energy, transport that prevent investors from investing in Malawi in high-potential sectors.
- Second, the fundamental cause of the short-term macroeconomic crisis is a fiscal deficit that results in excess money creation and, thus, in exchange rate pressure, inflation, and accumulation of domestic debt. Malawi’s government has taken on spending responsibilities it cannot fund with current tax levels and has financed this gap with a combination of expensive debt and printing by the Reserve Bank of Malawi (RBM). These result in exchange rate pressure, inflation, and an unsustainable domestic debt spiral that threatens to turn into a banking crisis. Thus, solving the macro crisis will require a fiscal adjustment that puts Malawi on a sustainable fiscal path. There are some opportunities on primary expenditure reduction and reducing the high cost of debt services. But there will also need to be a concerted effort on revenue mobilization. With limited available data, it is unclear which tax-related strategies (closing loopholes vs. addressing tax evasion, for example) can have the biggest positive impact, especially in a short-term scenario of an economy under stress. However, international experience and the wider macroeconomic context of Malawi suggest that a bold focus on evasion may be the most important step. If revenue collection can overdeliver, this reduces the need for domestic borrowing and money creation, which makes addressing inflation and the debt path more achievable. Clearer and more transparent fiscal strategies could help to crowd in additional donor budget support. A strong commitment and performance in this realm can also help re-establish credibility for Malawi among the international community.
- Third, addressing the current macroeconomic crisis and high inflation can only happen if money creation slows. Food price shocks may have played an important role in price increases experienced in 2011-15, but this is not the driver of Malawi’s inflation over the last several years. Inflation is coming overwhelmingly from growth of the monetary base, which is a result of money creation. Money creation has been used to fill a fiscal gap that is occurring at unprecedented levels. Bringing down inflation will be impossible without slowing growth of base money by the RBM, which in turn means slowing government borrowing from the RBM. This suggests that the monetary base or the value of net domestic assets may be viable to use as a policy anchor. Meanwhile, issues in food supply and farmer productivity are an ongoing risk. Malawi has available policy options to increase agricultural productivity and food security that have yet to be mobilized to address food supply risks. Food security will be a key concern in the short run. This note, however, focuses on the underlying economic causes of Malawi’s current macroeconomic predicament, long-term lack of growth, and recurring food insecurity.
- Fourth, domestic debt is a ticking time bomb that risks turning into a banking crisis. Sustainability requires dealing with both the high price of the stock of domestic debt and the flow of new domestic debt. Any path to growth and any credible fiscal adjustment will require lowering the growing interest rate burden of Malawi’s debt and getting back to debt sustainability. However, this will not be achieved through external debt reprofiling or debt forgiveness alone. What most undermines Malawi’s current situation is the ballooning path of domestic debt accumulation. High domestic borrowing raises rollover risks, keeps interest costs elevated, and pressures the RBM to finance the deficit, thereby fueling inflation and eroding policy credibility. A large and growing share of the fiscal deficit is now explained by interest payments on this debt, creating a vicious cycle of borrowing to service past borrowing. Unless this cycle is addressed, there will be little other fiscal space, and fiscal adjustment will not be possible. External debt operations can play a supportive role, but only if pursued alongside credible fiscal consolidation and declining money growth. There is also limited room for such borrowing to continue, and if the government cannot use this channel to borrow, then it will be forced to either inflate away the debt with hyperinflation or default, resulting in a larger banking crisis.
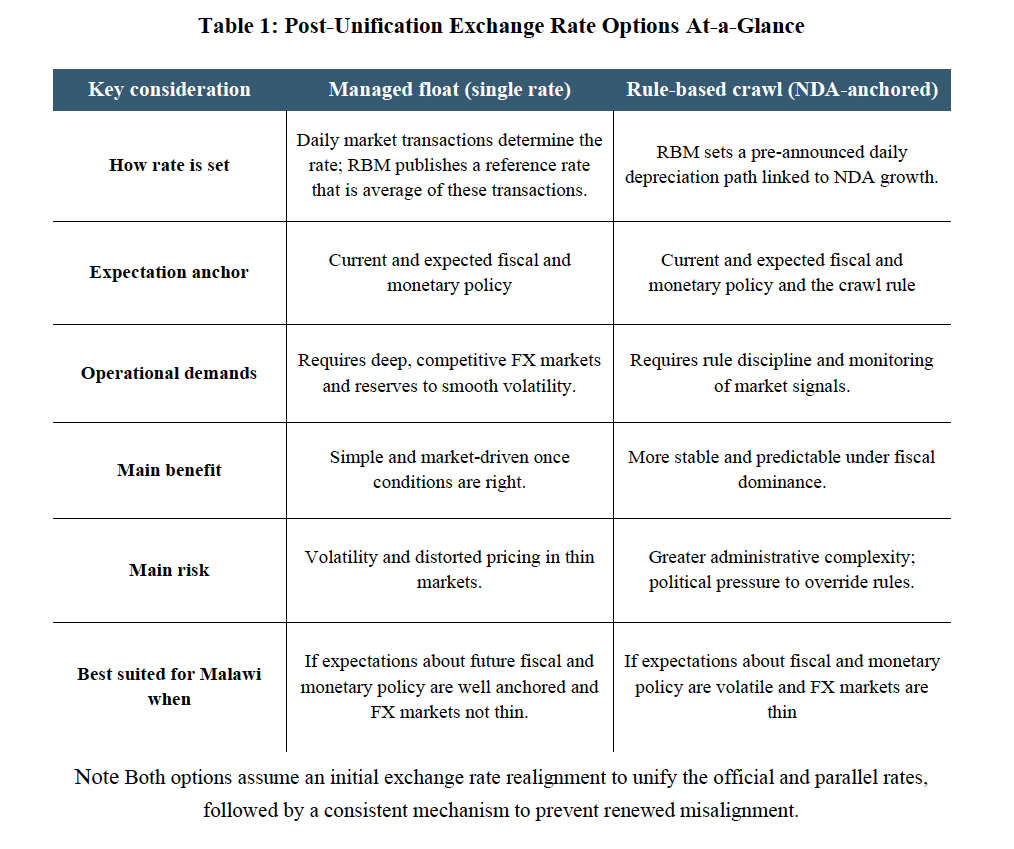
- Fifth, the current exchange rate system is not working in terms of stated goals as a macroeconomic anchor. Meanwhile, it is disincentivizing exports and investment making the overall macroeconomic challenges worse. The parallel market has grown as a second-best way for actors in the economy to access foreign exchange. Rather than being a hinderance, it is providing a release valve. At this point, most imports are made at the parallel-market rate, meaning that much of the economy is already off the official rate. Excess money in circulation is leading directly to depreciation of the kwacha in the parallel market and to inflation. Thus, there is more space for policy change than commonly appreciated, especially if there is a clear strategy to deal with the fuel sector which is one of the major sectors to continue to use the official rate. Distortions across the economy from prolonged (and growing) scarcity of officially supplied foreign exchange is a top constraint that holds back the development of new exporters. Rationing of imports at the official exchange rate, and through outright restrictions, not only undermines imported inputs and investment by would-be exporters but also has created an inward-oriented economy that centers on government and donors as markets. Given the consequences on the real economy and the ineffectiveness of the current anchor, the path forward on exchange rate management should be an area of detailed planning and potential experimentation rather than a debate between extremes of a current policy and a free-floating rate.
The goal of this policy note is to provide inputs for Malawian policymakers to develop a truly homegrown reform plan and initial path to growth, which could be leveraged to crowd in short-term support of the IMF and other international institutions. Malawi risks an acute macroeconomic crisis alongside constraints that have undermined growth for decades. History shows that effective approaches in economic circumstances like this cannot be externally driven; they must be homegrown. Malawian leaders need to have a clear understanding of the origins, causes, and consequences of macroeconomic challenges, and the boldness to act on challenges with evidence. Likewise, when governments put forth evidence-based strategies for change and make good faith requests for support, it is the responsibility of international development organizations to help. With these two ingredients, a path out of poverty and toward prosperity is possible.
There may be a window of opportunity to use the current crisis and a potential future IMF program to implement both macroeconomic and investment reforms that could put Malawi on a higher growth path. To replenish buffers and reserves, and regain the confidence of donors and external lenders, Malawi will need external financing from the IMF. This financing will come with its set of conditionalities. Usually, the dynamic is one where these conditions are imposed on a developing country. But there is an opportunity, instead, to proactively approach the IMF with a clear plan. This plan must make difficult choices on issues like the budget and exchange rate. But such a program can also be an opportunity. It can be the moment to make the reforms to both the macroeconomic and investment environment that allows it to grow into the future, credibly showing investors across the world that Malawi is a place where they can thrive. To do so, will require a focused strategy on what reforms are critical and taking advantage of opportunities as they arise.