Repository
Search
Policy Area
Format
Country/Region
Year
Research Project
Research Type
Author
-
Journal Articles
Economic Integration and Upward Mobility in Brazil
Are cities in emerging economies poverty traps or engines of opportunity? We use 13 years of linked employer–employee data covering all formal workers in Brazil to explore the mechanisms through […]
Are cities in emerging economies poverty traps or engines of opportunity? We use 13 years of linked employer–employee data covering all formal workers in Brazil to explore the mechanisms through which agglomeration promotes mobility for initially poor workers. We find that the cities that appear to enable more upward mobility in Brazil’s south are characterized by greater mixing of skilled and unskilled labor than similarly sized cities with less mobility in the north, where skilled workers disproportionately concentrate in the public sector. These findings suggest that the benefits of urbanization stem not only from the size of the agglomeration or its level of formal schooling but also from the social organization of production.
-
Journal Articles
The Gender Dimension of Refugees’ Integration in the Labor Market
This paper examines the gender differences in labor market integration among refugees and their determinants. It focuses on a longitudinal dataset that covers the entire refugee population in Switzerland over […]This paper examines the gender differences in labor market integration among refugees and their determinants. It focuses on a longitudinal dataset that covers the entire refugee population in Switzerland over 20 years. During the period examined, the majority of refugees came from low-income economies in Africa and Asia. The quasi-random allocation of asylum seekers across Swiss cantons, which differ in their socio-economic characteristics, provides a natural experiment to identify the effects of source country culture and the role of local initial conditions in shaping refugees’ labor-market integration trajectories. Our empirical findings show that women refugees from countries with more conservative gender norms (measured by female-to-male labor force participation ratios and fertility rates) have less favorable labor market outcomes, with these effects varying in their persistence over time. The analysis further reveals the negative role of initial unemployment and the positive role of co-ethnic networks in the cantons of arrival, with these effects varying by gender and network characteristics. Finally, local attitudes toward gender equality reduce the gender gap in labor market outcomes among refugees.
-
Working Papers
Competitiveness and Opportunities for European Clean Tech
Though Europeans have pioneered many green technologies, Europe is currently losing some competitiveness in the production of those technologies. This slowdown affects different countries and regions differently. Boosting competitiveness at […]Though Europeans have pioneered many green technologies, Europe is currently losing some competitiveness in the production of those technologies. This slowdown affects different countries and regions differently. Boosting competitiveness at the aggregate level should therefore involve approaches that take into account diverse regional industrial capabilities.
In this paper, we evaluate Europe’s positioning in green technologies and identify opportunities for Europe to translate its industrial capabilities into leadership of green value chains. We use two datasets – the Greenplexity dataset from the Harvard Growth Lab, and the European Clean Tech Tracker from Bruegel (Growth Lab, 2025; Bruegel Dataset, 2025) – to explore trends at national and regional levels.
We identify the sectors and regions in which Europe can strengthen its position, build competitiveness in new industries and generate economic growth through the energy transition. We conclude with policy priorities for guiding clean-technology investments, arguing that policymakers should use the feasibility and attractiveness of industrial clusters to target investment support at the regional level.
This paper is also published as a Bruegel Working Paper. Issue number 28/2026, available at https://doi.org/10.64153/ZYKB9779.
-
Working Papers
Resolving Malawi’s Binding Foreign Exchange Constraint
This research note diagnoses the causes behind Malawi’s foreign exchange constraint and identifies options for addressing the problem. Malawi is currently experiencing a severe and prolonged macroeconomic crisis, characterized by […]This research note diagnoses the causes behind Malawi’s foreign exchange constraint and identifies options for addressing the problem. Malawi is currently experiencing a severe and prolonged macroeconomic crisis, characterized by declining per capita income, crippling foreign exchange shortages, high inflation, and a rapidly growing (domestic) debt burden. Multi-faceted macroeconomic reforms are needed (see Growth Lab’s previous report, “Malawi’s Path out of Poverty and Toward Prosperity”). However, we find that relaxing extreme foreign exchange shortages by achieving a market-clearing rate could be achieved relatively quickly. The gains of this reform would be large, and the risks would be limited if the exchange rate realignment is matched with consistent monetary and fiscal policy. This note explains this path.
Excess money creation is the cause of both the high and increasing parallel market premium for foreign exchange and high inflation in Malawi today. Since 2020, the monetary base has expanded by a factor of four as the government has relied on the Reserve Bank of Malawi (RBM) to finance its large fiscal deficits. This has resulted in an increasing supply of Kwacha “chasing” a limited supply of dollars, which has caused a rising parallel market premium for foreign exchange. Much of the economy has, in practice, already shifted to the parallel rate, which means that the pass-through of a devaluation of the official rate on inflation would be limited. Previous one-off devaluations failed to address the parallel market premium because they did not align the path of the official exchange rate with that of money growth. Meanwhile, cracking down on the parallel market without addressing underlying causes also will not work because actors in the economy desperate for foreign exchange will always try to find workarounds.
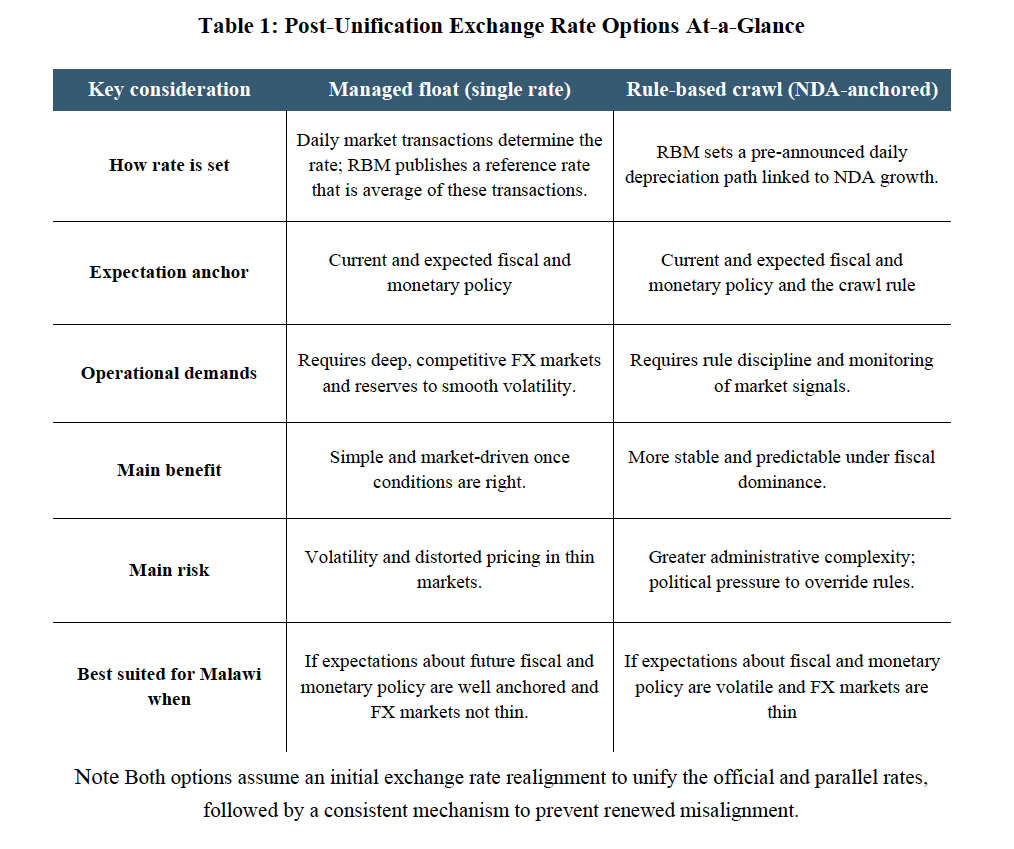
This paper discusses options for achieving a market-clearing exchange rate to end inefficient foreign exchange rationing and bring foreign currency back into official channels. This requires an initial sharp devaluation to unify the official and parallel rates, followed by a consistent policy to prevent renewed misalignment. Two operational paths are discussed as options: a managed float, where the rate is determined daily by bilateral market transactions, or a rule-based managed crawl, which anchors the daily adjustment of the exchange rate to the path of domestic liquidity growth (see Table 1). A full float and an end to capital controls is not advisable in the current context.
Foreign exchange reform is necessary but cannot fully succeed in isolation. Measures aimed at addressing the foreign exchange shortage can work in the short-term to relax this binding constraint on growth. But these measures alone cannot restore other macroeconomic balances. To achieve lower inflation, the Government of Malawi must reduce its primary deficit and limit the need for money printing. Furthermore, policymakers must manage the fiscal impact of devaluation and the transition of administered prices (such as fuel and fertilizer) from the overvalued official exchange rate. Failure to do so could result in a negative fiscal feedback loop, where devaluation necessitates more money printing. Macroprudential policy may also allow for a reduction in the domestic interest burden, and increased donor support would help enable macroeconomic stabilization and growth. In the long term, Malawi must diversify and grow its export sectors to generate more foreign exchange. Analysis discussing these necessary dimensions of overall macroeconomic reform are discussed in the three annexes, while the note focuses on the somewhat independent options that Malawi can use to meaningfully address the binding foreign exchange constraint that the economy currently faces.
-
Working Papers
Malawi’s Path Out of Poverty and Toward Prosperity
The Malawian economy is currently unable to grow despite the immense potential of its people. Per capita income has been declining since 2020, while poverty remains amongst the highest in […]The Malawian economy is currently unable to grow despite the immense potential of its people. Per capita income has been declining since 2020, while poverty remains amongst the highest in the world. Equally problematic, Malawi’s growth over the preceding decade was wholly insufficient to keep pace with the rest of the global economy. This kept Malawian per capita income at less than 1% of the U.S. level. Unless problems that have been allowed to fester are reversed, most Malawian families will continue to be subjected to poverty and extreme vulnerability, today and potentially for generations to come. Worse, Malawi is in the midst of a slow-moving macroeconomic crisis which could become deeper and more acute if access to foreign exchange collapses further.
Reversing the course of the national economy is ultimately about putting Malawians in a position to pursue opportunities that are currently held back. Even as the nation has faced nearly annual climate-related shocks, Malawians are resilient. It is their access to productive economic networks that holds back opportunity. Other countries such as Rwanda and Ethiopia that are landlocked, face weather shocks, and were recently as poor as Malawi have been able to achieve accelerated growth paths through long-term investment and growth in exports. Malawians are meanwhile brimming with untapped potential, and Malawian businesses are as enterprising as any in the world. There are many potential opportunities for growth in Malawi from agriculture, mining, tourism, and others that are severely held back by macroeconomic circumstances.
Jumpstarting growth is impossible under current macroeconomic constraints. As growth has lagged, and as Malawi has been subjected to shocks, macroeconomic policy has been put in a bind, which has been increasingly tightening. As late 2025, Malawi faces foreign exchange shortages that have played a critical role in undermining the economy for several years. This shortage has come alongside high inflation, which is undermining the hard-earned incomes of Malawians. Recent investment levels have been insufficient for Malawi’s current needs and have been reliant on increasingly fickle donor support. Private investment is extremely low in Malawi. It is very difficult for both domestic and foreign investors to invest in Malawi’s potential when they cannot import the inputs they need or freely move in and out the dollars their export businesses generate, and when returns are at risk of being inflated away. While solving macroeconomic challenges alone will not create the dynamic export sectors that Malawi needs, it is a necessary condition.
The current macroeconomic environment is causing pain and hardship while putting Malawi in an even more vulnerable position. The government has lost access to external credit, leaving it reliant on a vicious cycle of domestic borrowing from banks at high cost and excess money creation to support current spending. Foreign exchange availability teeters on the edge of collapse, with import coverage measured in units of days or weeks. Access to foreign exchange and finance from domestic banks provides a tenuous lifeline, but this system will break at some point if the balance sheets of banks increasingly deteriorate. All the while, as macroeconomic policy targets survival rather than a strategy for addressing the core problems, the damage of these distortions on the economy and lives of everyday Malawians is immense. Macroeconomic anchors are currently ineffective, and Malawians are growing poorer each day. With buffers so thin, Malawi is one shock away from potentially being in an even worse crisis.
As a result, Malawi has two economic problems: a medium-term growth challenge and a short-term macroeconomic stabilization crisis. It is important to understand each of these clearly and how they interact. This note points to several key observations on the growth challenge and the path out of the macroeconomic crisis. The report is organized around five key conclusions, which do not neatly align with the stated understanding of the Government of Malawi nor that of international development community in all cases.
- First, the path to growth will hinge on expanding exports. Malawi has gotten to this critical point because its traditional sources of foreign exchange (e.g., tobacco and aid) have stagnated or declined while its population grows, and it is hit by increasingly more frequent shocks. Since 2012, this has led to three distinct phases of macroeconomic management to live within lesser means. Growth will require a steady increase in export generation, and strategies should thus pay special attention to what holds back the growth of existing and new exporters. The current macroeconomic regime is clearly untenable but a return to previous regimes is also no longer possible. The regime that allowed for a fixed exchange rate and low inflation over 2017-2020 is no longer possible because it relied on positive net foreign reserves that were available at the time. Policymakers will need to develop a new path that is built on generating exports and foreign investment. Such a path will need to both solve the current macro issues and remove restrictions and barriers in areas like land, access to energy, transport that prevent investors from investing in Malawi in high-potential sectors.
- Second, the fundamental cause of the short-term macroeconomic crisis is a fiscal deficit that results in excess money creation and, thus, in exchange rate pressure, inflation, and accumulation of domestic debt. Malawi’s government has taken on spending responsibilities it cannot fund with current tax levels and has financed this gap with a combination of expensive debt and printing by the Reserve Bank of Malawi (RBM). These result in exchange rate pressure, inflation, and an unsustainable domestic debt spiral that threatens to turn into a banking crisis. Thus, solving the macro crisis will require a fiscal adjustment that puts Malawi on a sustainable fiscal path. There are some opportunities on primary expenditure reduction and reducing the high cost of debt services. But there will also need to be a concerted effort on revenue mobilization. With limited available data, it is unclear which tax-related strategies (closing loopholes vs. addressing tax evasion, for example) can have the biggest positive impact, especially in a short-term scenario of an economy under stress. However, international experience and the wider macroeconomic context of Malawi suggest that a bold focus on evasion may be the most important step. If revenue collection can overdeliver, this reduces the need for domestic borrowing and money creation, which makes addressing inflation and the debt path more achievable. Clearer and more transparent fiscal strategies could help to crowd in additional donor budget support. A strong commitment and performance in this realm can also help re-establish credibility for Malawi among the international community.
- Third, addressing the current macroeconomic crisis and high inflation can only happen if money creation slows. Food price shocks may have played an important role in price increases experienced in 2011-15, but this is not the driver of Malawi’s inflation over the last several years. Inflation is coming overwhelmingly from growth of the monetary base, which is a result of money creation. Money creation has been used to fill a fiscal gap that is occurring at unprecedented levels. Bringing down inflation will be impossible without slowing growth of base money by the RBM, which in turn means slowing government borrowing from the RBM. This suggests that the monetary base or the value of net domestic assets may be viable to use as a policy anchor. Meanwhile, issues in food supply and farmer productivity are an ongoing risk. Malawi has available policy options to increase agricultural productivity and food security that have yet to be mobilized to address food supply risks. Food security will be a key concern in the short run. This note, however, focuses on the underlying economic causes of Malawi’s current macroeconomic predicament, long-term lack of growth, and recurring food insecurity.
- Fourth, domestic debt is a ticking time bomb that risks turning into a banking crisis. Sustainability requires dealing with both the high price of the stock of domestic debt and the flow of new domestic debt. Any path to growth and any credible fiscal adjustment will require lowering the growing interest rate burden of Malawi’s debt and getting back to debt sustainability. However, this will not be achieved through external debt reprofiling or debt forgiveness alone. What most undermines Malawi’s current situation is the ballooning path of domestic debt accumulation. High domestic borrowing raises rollover risks, keeps interest costs elevated, and pressures the RBM to finance the deficit, thereby fueling inflation and eroding policy credibility. A large and growing share of the fiscal deficit is now explained by interest payments on this debt, creating a vicious cycle of borrowing to service past borrowing. Unless this cycle is addressed, there will be little other fiscal space, and fiscal adjustment will not be possible. External debt operations can play a supportive role, but only if pursued alongside credible fiscal consolidation and declining money growth. There is also limited room for such borrowing to continue, and if the government cannot use this channel to borrow, then it will be forced to either inflate away the debt with hyperinflation or default, resulting in a larger banking crisis.
- Fifth, the current exchange rate system is not working in terms of stated goals as a macroeconomic anchor. Meanwhile, it is disincentivizing exports and investment making the overall macroeconomic challenges worse. The parallel market has grown as a second-best way for actors in the economy to access foreign exchange. Rather than being a hinderance, it is providing a release valve. At this point, most imports are made at the parallel-market rate, meaning that much of the economy is already off the official rate. Excess money in circulation is leading directly to depreciation of the kwacha in the parallel market and to inflation. Thus, there is more space for policy change than commonly appreciated, especially if there is a clear strategy to deal with the fuel sector which is one of the major sectors to continue to use the official rate. Distortions across the economy from prolonged (and growing) scarcity of officially supplied foreign exchange is a top constraint that holds back the development of new exporters. Rationing of imports at the official exchange rate, and through outright restrictions, not only undermines imported inputs and investment by would-be exporters but also has created an inward-oriented economy that centers on government and donors as markets. Given the consequences on the real economy and the ineffectiveness of the current anchor, the path forward on exchange rate management should be an area of detailed planning and potential experimentation rather than a debate between extremes of a current policy and a free-floating rate.
The goal of this policy note is to provide inputs for Malawian policymakers to develop a truly homegrown reform plan and initial path to growth, which could be leveraged to crowd in short-term support of the IMF and other international institutions. Malawi risks an acute macroeconomic crisis alongside constraints that have undermined growth for decades. History shows that effective approaches in economic circumstances like this cannot be externally driven; they must be homegrown. Malawian leaders need to have a clear understanding of the origins, causes, and consequences of macroeconomic challenges, and the boldness to act on challenges with evidence. Likewise, when governments put forth evidence-based strategies for change and make good faith requests for support, it is the responsibility of international development organizations to help. With these two ingredients, a path out of poverty and toward prosperity is possible.
There may be a window of opportunity to use the current crisis and a potential future IMF program to implement both macroeconomic and investment reforms that could put Malawi on a higher growth path. To replenish buffers and reserves, and regain the confidence of donors and external lenders, Malawi will need external financing from the IMF. This financing will come with its set of conditionalities. Usually, the dynamic is one where these conditions are imposed on a developing country. But there is an opportunity, instead, to proactively approach the IMF with a clear plan. This plan must make difficult choices on issues like the budget and exchange rate. But such a program can also be an opportunity. It can be the moment to make the reforms to both the macroeconomic and investment environment that allows it to grow into the future, credibly showing investors across the world that Malawi is a place where they can thrive. To do so, will require a focused strategy on what reforms are critical and taking advantage of opportunities as they arise.
-
Journal Articles
Burning bridges or bridging divides: Geopolitics and collaboration in research and innovation
This paper analyzes the association between geopolitical alignment and international research and innovation collaborations using data spanning 2000–2023. Using ideal point distance measures derived from UN General Assembly voting patterns, […]This paper analyzes the association between geopolitical alignment and international research and innovation collaborations using data spanning 2000–2023. Using ideal point distance measures derived from UN General Assembly voting patterns, we find that increases in geopolitical distance are associated with reductions in international collaborations. A one-unit increase in geopolitical distance (roughly the distance between a median country pair) over three years is associated with a 3.1% reduction in collaborations in scientific publications (0.8% per standard deviation). We also find that this relationship is asymmetric: worsening geopolitical relations are associated with reductions in collaborations in scientific publications that are roughly three times larger than the gains associated with equivalent improvements, suggesting that international research partnerships are easier to damage than to build. At the technology level, critical technologies exhibit approximately three times the expected level of international collaboration compared to other fields (conditional on country-pair effects), yet are also more sensitive to shifts in geopolitical alignment, raising concerns about technology sovereignty. At the same time, despite ongoing geopolitical tensions, overall collaboration patterns have not undergone substantial changes in recent years, suggesting resilience in international research and innovation networks.
-
Books
Canada After America
For generations, Canada built its prosperity on economic integration with the United States, only to find itself hostage to its nearest neighbor.In Canada After America, economists Ricardo Hausmann and Eric […]
For generations, Canada built its prosperity on economic integration with the United States, only to find itself hostage to its nearest neighbor.
In Canada After America, economists Ricardo Hausmann and Eric Protzer offer a bold, practical strategy for Canadian prosperity in a radically changed world.Drawing on research from the Harvard Growth Lab and the insights of economic complexity, they argue that the answer is not to retreat from globalization, but to become far better at competing in the rest of the world. Canada must get more of its natural resources to global markets while building industries—aerospace, life sciences, technology—that can overcome the tyranny of distance.
It won’t be easy. Despite world-class universities and research, Canada’s private-sector knowledge economy remains stunted. The country has failed to build and sustain large, research-intensive companies and the dynamic cities in which they flourish. It must abandon its “small is beautiful” approach to innovation, remove barriers to growth, and enable its most promising firms to scale.
The rupture with America is a crisis—but also a historic opportunity to build a more innovative, resilient, and globally competitive Canada.
-
Working Papers
A Change of Denomination: The Case for CPI-Indexed World Bank Lending
This paper asks whether the World Bank can change the denomination of its lending without weakening its own financial position. Using monthly CPI and exchange rate data, we construct the […]
This paper asks whether the World Bank can change the denomination of its lending without weakening its own financial position. Using monthly CPI and exchange rate data, we construct the dollar returns the Bank would earn on loans indexed to borrowers’ domestic inflation and aggregate those returns using current IBRD and IDA portfolio weights. Portfolio returns are less volatile because cross-country correlations are low. The diversification dividend is large enough to make the financially indifferent coupon on a CPI-indexed instrument close to, and in some cases below, current lending rates. The World Bank can reduce one of the core sources of macroeconomic instability in borrowing countries at little or no financial cost to itself. -
Web Articles
Argentina’s second test: can the Milei government deliver lasting growth?
Economics Observatory
President Milei’s stabilisation is delivering results: inflation is down, growth has returned and exports are playing a larger role in the recovery. But Argentina’s second test is harder: turning macroeconomic […]President Milei’s stabilisation is delivering results: inflation is down, growth has returned and exports are playing a larger role in the recovery. But Argentina’s second test is harder: turning macroeconomic stability into investment, jobs and higher real wages before the political clock runs out.
-
Journal Articles
Raising the Bar: An Inclusive Global Poverty Line
The first of the United Nations 2015 Sustainable Development Goals is: “End poverty in all its forms everywhere.” An implication of this broad goal is the existence of an array […]The first of the United Nations 2015 Sustainable Development Goals is: “End poverty in all its forms everywhere.” An implication of this broad goal is the existence of an array of poverty lines, which raises the question of an appropriate lower-bound and an upper-bound to global poverty lines. The ‘dollar-a-day’ poverty line (updated for inflation to P$2.15 in 2017 PPP) is widely accepted as a global lower-bound poverty line (GLBPL). However, while different countries, organizations, and authors use higher poverty lines, there is no consensus on a global upper bound poverty line (GUBPL). We estimate a GUBPL using two conceptually distinct approaches, both grounded in the tension between the focus axiom for poverty measures and standard economic social welfare measures. We set a candidate GUBPL either at: (i) the consumption consistent with the achievement of adequate material well-being or (ii) the consumption level where marginal utility is “near enough” zero. Using either approach, empirical results across an array of measures of well-being demonstrate that ad hoc poverty lines, including the World Bank’s highest reported poverty line of P$6.85, are far too low to be plausible candidates for a GUBPL. Using the two approaches across four distinct indicators of well-being all of the empirical results suggest a GUBPL of at least P$21.5, ten times higher than the standard GLPBL of P$2.15. The use of both a lower bound and upper bound global poverty line balances the radically exclusive nature of the ‘dollar-a-day’ standard, which classifies people with very low levels of material well-being and hence very high marginal utility of income as “not poor” with an equally radically inclusive GUBPL which counts only those with globally high material achievement and low (ish) marginal utility of income as “not poor.”
UNU-WIDER blog: Raising the bar – an inclusive poverty line